Distributed Density Filtering for Large-Scale Systems Using Mean-Filed Models
Tongjia Zheng, Hai Lin
Abstract
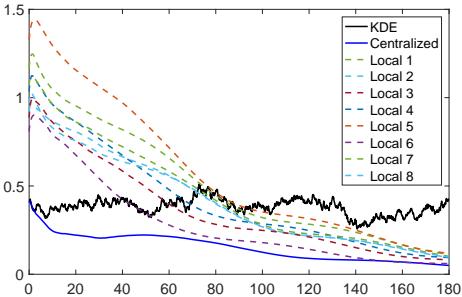
— This work studies distributed (probability) density estimation of large-scale systems. Such problems are motivated by many density-based distributed control tasks in which the real-time density of the swarm is used as feedback information, such as sensor deployment and city traffic scheduling. This work is built upon our previous work [1] which presented a (centralized) density filter to estimate the dynamic density of large-scale systems through a novel integration of meanfield models, kernel density estimation (KDE), and infinitedimensional Kalman filters. In this work, we further study how to decentralize the density filter such that each agent can estimate the global density only based on its local observation and communication with neighbors. This is achieved by noting that the global observation constructed by KDE is an average of the local kernels. Hence, dynamic average consensus algorithms are used for each agent to track the global observation in a distributed way. We present a distributed density filter which requires very little information exchange, and study its stability and optimality using the notion of input-to-state stability. Simulation results suggest that the distributed filter is able to converge to the centralized filter and remain close to it.
§ The Valyu brief
Reading the full paper and taking notes. This takes a few seconds…
§ Ask this paper
Ask a question about this paper
Valyu reads the full text and answers from what the paper actually says.
Searching the other archives…