Periodically correlated time series and the Variable Bandpass Periodic Block Bootstrap Periodic correlation and the Variable Bandpass Periodic Block Bootstrap
Edward L. Valachovic, Nattapol Aunsri
Abstract
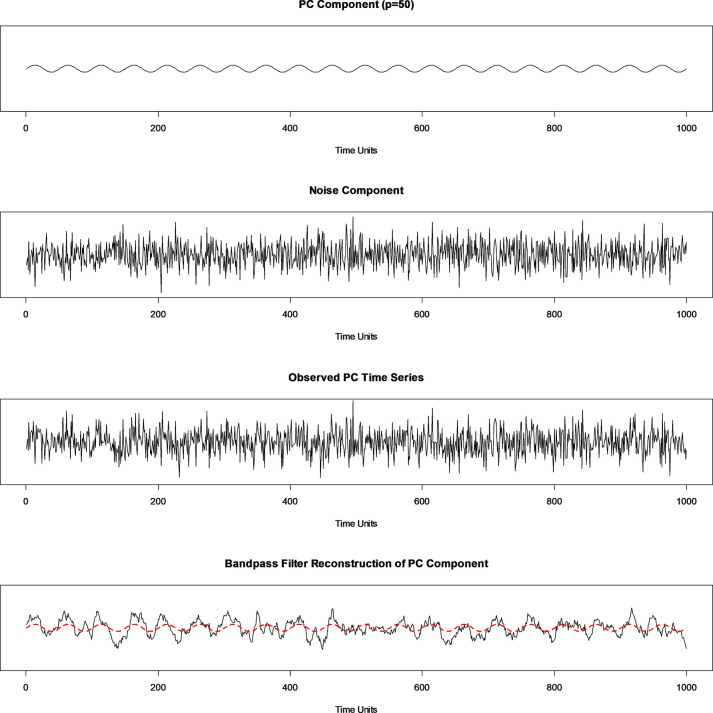
This research introduces a novel approach to resampling periodically correlated time series using bandpass filters for frequency separation called the Variable Bandpass Periodic Block Bootstrap and then examines the significant advantages of this new method. While bootstrapping allows estimation of a statistic’s sampling distribution by resampling the original data with replacement, and block bootstrapping is a model-free resampling strategy for correlated time series data, both fail to preserve correlations in periodically correlated time series. Existing extensions of the block bootstrap help preserve the correlation structures of periodically correlated processes but suffer from flaws and inefficiencies. Analyses of time series data containing cyclic, seasonal, or periodically correlated principal components often seen in annual, daily, or other cyclostationary processes benefit from separating these components. The Variable Bandpass Periodic Block Bootstrap uses bandpass filters to separate a periodically correlated component from interference such as noise at other uncorrelated frequencies. A simulation study is presented, demonstrating near universal improvements obtained from the Variable Bandpass Periodic Block Bootstrap when compared with prior block bootstrapping methods for periodically correlated time series.
§ The Valyu brief
Reading the full paper and taking notes. This takes a few seconds…
§ Ask this paper
Ask a question about this paper
Valyu reads the full text and answers from what the paper actually says.
Searching the other archives…