A Feature Fusion Based Forecasting Model for Financial Time Series A Model for Financial Time Series Forecasting
Zhiqiang Guo, Huaiqing Wang, Quan Liu, Jie Yang, Alejandro Raul Hernandez Montoya
Abstract
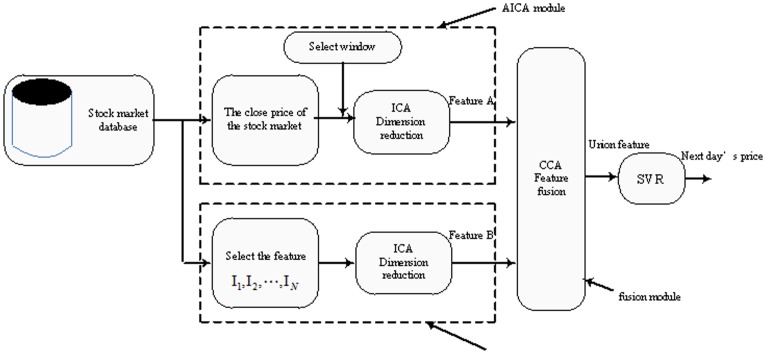
'Alejandro Raul Hernandez Montoya'] Predicting the stock market has become an increasingly interesting research area for both researchers and investors, and many prediction models have been proposed. In these models, feature selection techniques are used to pre-process the raw data and remove noise. In this paper, a prediction model is constructed to forecast stock market behavior with the aid of independent component analysis, canonical correlation analysis, and a support vector machine. First, two types of features are extracted from the historical closing prices and 39 technical variables obtained by independent component analysis. Second, a canonical correlation analysis method is utilized to combine the two types of features and extract intrinsic features to improve the performance of the prediction model. Finally, a support vector machine is applied to forecast the next day's closing price. The proposed model is applied to the Shanghai stock market index and the Dow Jones index, and experimental results show that the proposed model performs better in the area of prediction than other two similar models.
§ The Valyu brief
Reading the full paper and taking notes. This takes a few seconds…
§ Ask this paper
Ask a question about this paper
Valyu reads the full text and answers from what the paper actually says.
Searching the other archives…