Estimation of Clustering Parameters Using Gaussian Process Regression Estimation of Clustering Parameters Using Gaussian Process Regression
Paul Rigby, Oscar Pizarro, Stefan B. Williams, Freddie Salsbury Jr
Abstract
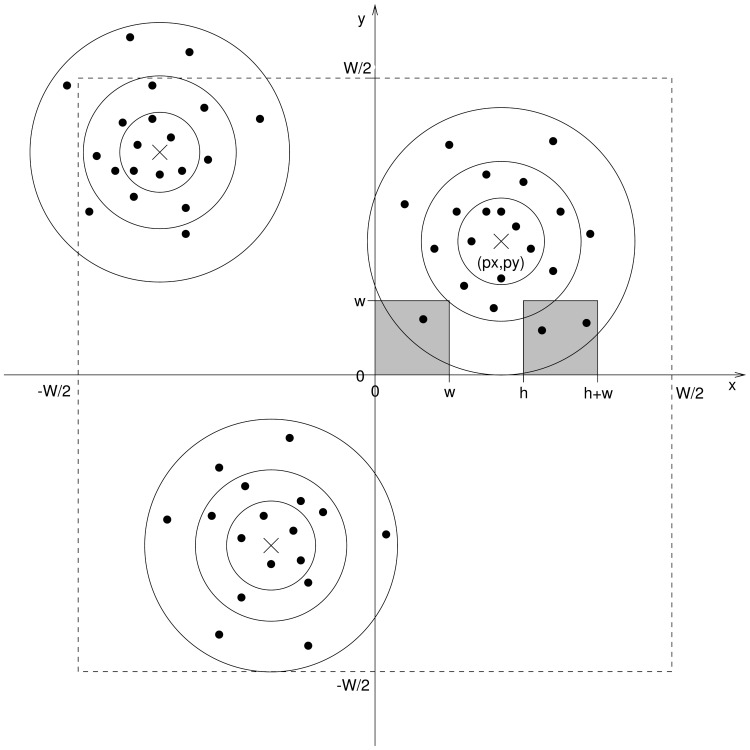
We propose a method for estimating the clustering parameters in a Neyman-Scott Poisson process using Gaussian process regression. It is assumed that the underlying process has been observed within a number of quadrats, and from this sparse information the distribution is modelled as a Gaussian process. The clustering parameters are then estimated numerically by fitting to the covariance structure of the model. It is shown that the proposed method is resilient to any sampling regime. The method is applied to simulated two-dimensional clustered populations and the results are compared to a related method from the literature.
§ The Valyu brief
Reading the full paper and taking notes. This takes a few seconds…
§ Ask this paper
Ask a question about this paper
Valyu reads the full text and answers from what the paper actually says.
Searching the other archives…