Spatial Autocorrelation Approaches to Testing Residuals from Least Squares Regression Testing for Serial Spatial Auto-Correlation in Regression Analysis
Yanguang Chen, Guy J-P. Schumann
Abstract
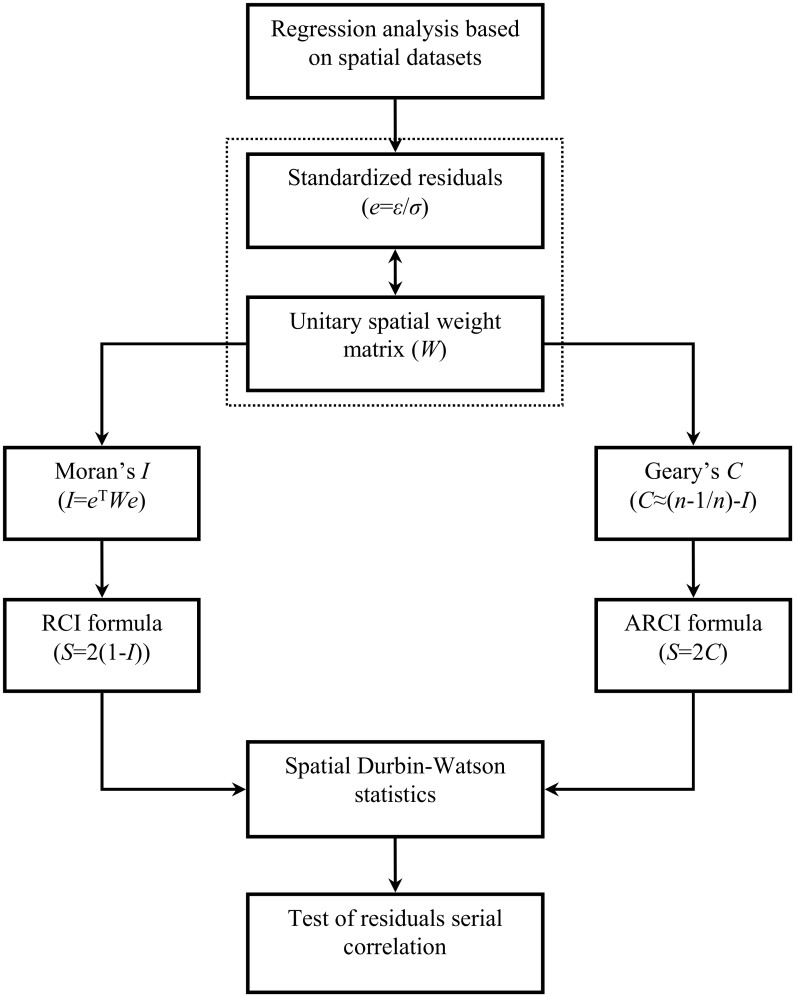
In geo-statistics, the Durbin-Watson test is frequently employed to detect the presence of residual serial correlation from least squares regression analyses. However, the Durbin-Watson statistic is only suitable for ordered time or spatial series. If the variables comprise cross-sectional data coming from spatial random sampling, the test will be ineffectual because the value of Durbin-Watson’s statistic depends on the sequence of data points. This paper develops two new statistics for testing serial correlation of residuals from least squares regression based on spatial samples. By analogy with the new form of Moran’s index, an autocorrelation coefficient is defined with a standardized residual vector and a normalized spatial weight matrix. Then by analogy with the Durbin-Watson statistic, two types of new serial correlation indices are constructed. As a case study, the two newly presented statistics are applied to a spatial sample of 29 China’s regions. These results show that the new spatial autocorrelation models can be used to test the serial correlation of residuals from regression analysis. In practice, the new statistics can make up for the deficiencies of the Durbin-Watson test.
§ The Valyu brief
Reading the full paper and taking notes. This takes a few seconds…
§ Ask this paper
Ask a question about this paper
Valyu reads the full text and answers from what the paper actually says.
Searching the other archives…